As credit unions outpace banks in auto lending, new research reveals that falling delinquency rates aren’t necessarily translating into fewer delinquent dollars or lower loan losses.
–
November 4, 2026 — Credit unions are expanding their auto loan portfolios considerably faster than banks, and at first glance, their credit performance appears to be improving. But a closer examination of recently released lending data reveals a troubling contradiction: While delinquency percentages are declining, the actual dollars delinquent have barely budged, and charge-offs remain elevated.
Two reports released this week, one from Equifax and another analyzing National Credit Union Administration (NCUA) Call Report data, suggest that rapid portfolio growth may be making credit union auto loan performance appear healthier than the underlying numbers indicate.
–
Credit Unions Lead Auto Lending Growth
According to Equifax’s November 2 analysis, credit unions increased their outstanding auto loan balances by 7% year over year to $498.6 billion through August 2026.
Banks, by comparison, experienced just 0.5% growth, while captive finance companies saw their portfolios contract 1.7%.
Across all lenders, outstanding auto debt reached $1.7 trillion, increasing 3.3% despite a 1.9% decline in the number of loans originated.
In other words, lenders are financing fewer vehicles but carrying larger loan balances.
Equifax also reported improving credit union delinquency performance, with 60-plus-day delinquency rates declining approximately 4.8% year over year.
That sounds encouraging. But another report suggests those percentages aren’t telling the entire story.
–
Delinquency Rates Fall, But Delinquent Dollars Don’t
A November 3 analysis by QuarterCall Research examined NCUA Call Report filings from 4,143 credit unions that reported continuously between the third quarters of 2024 and 2026.
The findings reveal a significant distinction between improving delinquency ratios and actual reductions in delinquent loans.
During the year ending September 30, 2026:
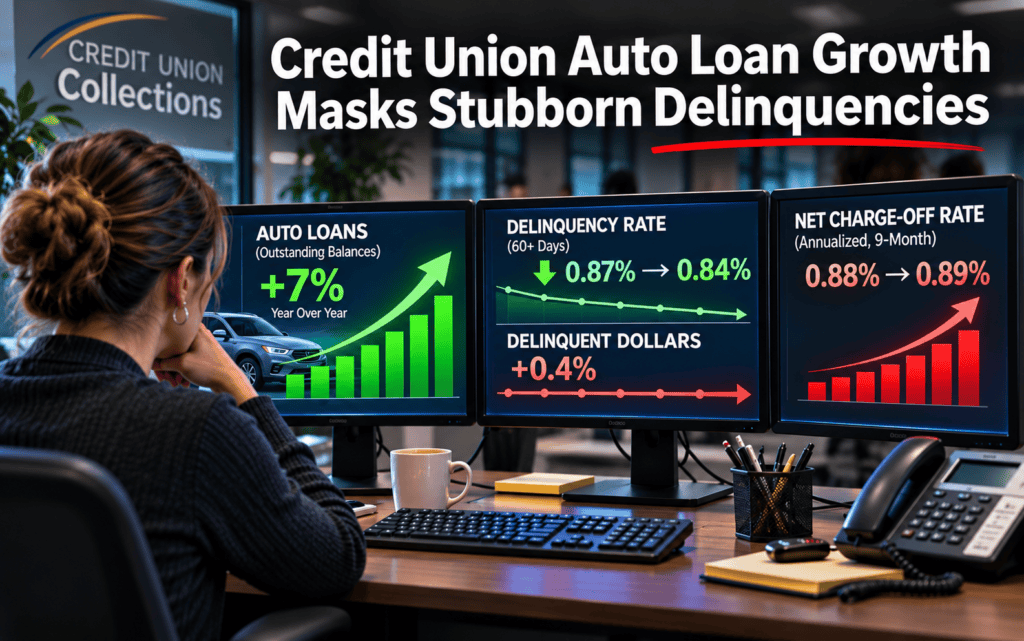
- Outstanding vehicle loans increased 3.92% to $487.7 billion.
- The 60-plus-day delinquency ratio declined from 0.87% to 0.84%.
- Actual delinquent vehicle loan balances increased 0.4%.
- The annualized nine-month net charge-off rate increased slightly from 0.88% to 0.89%, compared with 0.83% two years earlier.
The explanation is relatively simple.
When a credit union’s loan portfolio grows faster than its delinquent balances, the delinquency percentage declines even if the institution still has the same amount of troubled debt to collect.
That doesn’t mean the delinquency improvement is entirely artificial. Some credit unions experienced declining delinquency ratios even as their portfolios contracted. But across the combined group, delinquent dollars did not decline.
For collections departments, that distinction matters.
A lower delinquency percentage does not necessarily mean fewer delinquent accounts, smaller collection balances, reduced staffing requirements or fewer potential repossessions.
–
The Largest Credit Unions Show Additional Weakness
Perhaps more concerning is the difference in performance among credit unions of various sizes.
QuarterCall found that among the 20 credit unions with assets exceeding $10 billion, the vehicle loan delinquency ratio actually increased from 1.03% to 1.08%.
Their annualized nine-month net charge-off rate also rose from 1.02% to 1.13%.
Meanwhile, credit unions with assets between $1 billion and $10 billion reported improving vehicle loan delinquency rates, declining from 0.80% to 0.74%.
These differences suggest that the industry’s overall performance figures may conceal meaningful variations in credit quality among institutions.
They also raise questions about how aggressively some lenders are expanding their auto portfolios and whether their collections performance is keeping pace.
–
Bigger Balances, Persistent Collection Risks
The findings arrive as the broader auto finance industry continues to struggle with affordability, longer loan terms and elevated losses among financially stressed borrowers.
Larger financed balances can create additional exposure when borrowers default, particularly when the outstanding loan balance exceeds the vehicle’s recoverable value.
For credit unions, the concern extends beyond the delinquency ratio itself.
A growing portfolio may temporarily improve percentage-based performance measures, while older loans continue to deteriorate and newly originated loans have not yet had sufficient time to demonstrate their repayment performance.
This does not establish that credit unions are concealing losses or that their lending practices are becoming uniformly riskier. But it does underscore the importance of examining actual delinquent balances, loan vintages, charge-offs and recovery performance alongside traditional delinquency ratios.
There is also an important distinction between the two reports. Equifax measures credit-bureau lending activity through August, while QuarterCall analyzes a fixed group of credit unions using NCUA Call Reports through September. Their growth rates are not directly interchangeable.
–
A Warning for Credit Union Collections
For credit union executives and collections managers, the lesson is straightforward: A declining delinquency percentage is welcome news, but it should never be the only measure of portfolio health.
If delinquent dollars remain unchanged while the portfolio expands, the underlying collections burden may remain just as substantial.
And if charge-offs continue rising, even modestly, improving delinquency ratios may offer little comfort.
Credit unions are clearly gaining ground in auto lending. The question is whether that growth represents improving credit performance or is simply making persistent collection problems look smaller on paper.
Because when the portfolio gets bigger, the delinquency percentage can get smaller without a single additional dollar being collected.
Sources:
- Equifax — Auto Lending Trends 2026: Rising Balances, Improving Credit Performance, and Emerging Payment Risk — November 2, 2026.
- QuarterCall Research — The Ratio Fell, the Losses Did Not: Q3 2026 — November 3, 2026.
- NCUA — Credit Union Call Report Data.
Credit Union Auto Loan Growth Masks Stubborn Delinquencies – Credit Union Auto Loan Growth Masks Stubborn Delinquencies – Credit Union Auto Loan Growth Masks Stubborn Delinquencies
Credit Union Auto Loan Growth Masks Stubborn Delinquencies – Lending – Auto Loan – Delinquency – Credit Union Collections – Credit Union Collectors – NCUA – NCUA

More Stories
Credit Union Hardship Modifications Surge 23% as Navy Federal Accounts for Much of the Increase
Gunman Kills One in Rampage over $2,556 Citibank Credit Card Debt
NCUA Plans $4.3 Million AI Push to Detect Fraud
Fake Loans and Dead Members’ Accounts: NCUA Bans Two Former Credit Union Employees
CCUCC Honors Industry Leaders at Record-Setting Anaheim Conference
Argos Risk Announces Partnership with Credit Union Loan Source