Federal appeals court sides with credit union leasing company over consumer in dispute that highlights the legal differences between vehicle ownership, financing, and insurance proceeds.
–
When an insurance company declares a leased vehicle a total loss and pays off the outstanding balance owed to a credit union, who should receive the remaining insurance proceeds? The consumer who made the lease payments and maintained the insurance, or the leasing company that legally owned the vehicle?
That question was at the center of a federal appeals court decision issued November 20, 2026, involving Visions Federal Credit Union, Credit Union Leasing of America (CULA), and more than $10,000 in disputed insurance proceeds.
In Ajayi v. CULA, LLC, the U.S. Court of Appeals for the Third Circuit affirmed the dismissal of a proposed class action brought by a New Jersey consumer who argued that the leasing company improperly retained insurance proceeds remaining after the credit union’s financial interest had been satisfied.
The decision highlights an important distinction for credit union collections and collateral recovery departments: Paying off the financial obligation on a leased vehicle does not necessarily extinguish the leasing company’s ownership interest in the collateral.
–
A Total Loss and $10,550 Left Over
In June 2022, Adenike Ajayi leased a Toyota RAV4 Hybrid through a New Jersey dealership. Visions Federal Credit Union financed the transaction, while CULA served as the vehicle’s titled owner and lessor.
Approximately four months later, the vehicle was involved in an accident and declared a total loss.
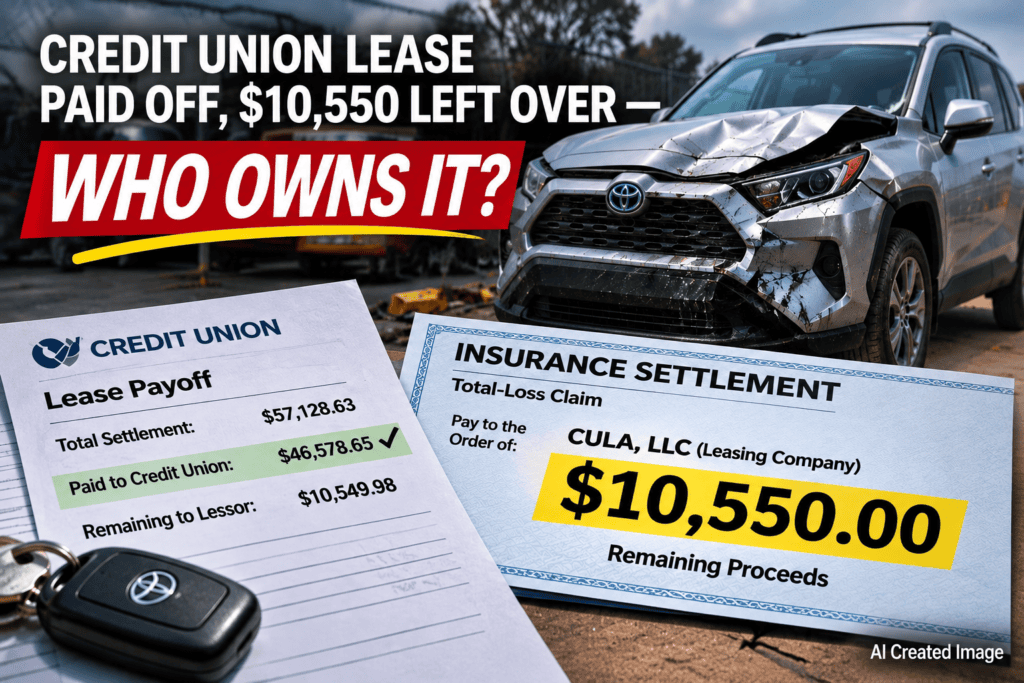
GEICO determined the vehicle’s total-loss settlement value to be $57,128.63.
Of that amount, $46,578.65 was paid to Visions Federal Credit Union to satisfy the outstanding lease balance. The remaining $10,549.98 went to CULA.
Ajayi received none of the insurance settlement.
She subsequently challenged CULA’s right to retain the remaining proceeds, arguing that once the outstanding financial obligation had been satisfied, the leasing company had no legitimate claim to the additional money.
Her proposed class action alleged breach of contract, breach of fiduciary duty, breach of the implied covenant of good faith and fair dealing, and violations of the New Jersey Consumer Fraud Act.
The courts rejected those arguments.
–
The Difference Between a Loan and a Lease
For credit union collections professionals, the distinction between financing a vehicle purchase and financing a vehicle lease is central to understanding the ruling.
In a conventional auto loan, the borrower generally owns the vehicle, subject to the lender’s security interest. When a total-loss insurance settlement exceeds the outstanding loan balance, the remaining proceeds ordinarily belong to the vehicle owner, subject to the insurance contract and any other valid claims.
A lease operates differently.
Although the consumer makes monthly payments, maintains insurance, and possesses the vehicle, the leasing company generally retains legal ownership.
In this case, Visions Federal Credit Union held the financial interest associated with the lease, while CULA owned the vehicle itself.
The Third Circuit concluded that CULA’s ownership interest was not limited to the outstanding amount owed to the credit union. The leasing company’s entitlement to the vehicle’s value continued even after the credit union’s balance was satisfied.
The court also rejected the argument that CULA’s designation as a loss payee restricted its recovery to the unpaid financial obligation.
The ruling effectively distinguished between satisfying a debt and compensating the owner for the destruction of its property.
–
But Who Should Get the Excess?
The legal outcome does not necessarily settle the broader question of consumer expectations.
A consumer who makes lease payments, pays insurance premiums, and maintains coverage sufficient to replace the vehicle might reasonably assume that any insurance proceeds remaining after the financial obligation is satisfied would be returned to them.
But that assumption can conflict with the contractual and legal realities of vehicle leasing.
The consumer was paying for the use of a vehicle, not acquiring ownership of it. The leasing company, meanwhile, retained the vehicle’s residual ownership interest and stood to lose that asset when it was destroyed.
That distinction raises a question worth considering: Should the consumer’s responsibility for insuring the vehicle create any entitlement to insurance proceeds exceeding the lease payoff, or should the titled owner’s property interest control?
In this case, the courts determined that CULA’s ownership interest controlled.
The outcome should not be interpreted as establishing that every leasing company is automatically entitled to every dollar of excess insurance proceeds. Lease language, insurance provisions, applicable state law, and the parties’ respective interests remain important.
–
Implications for Credit Union Collections Departments
Although Visions Federal Credit Union was not a defendant and was not accused of wrongdoing, the dispute illustrates several considerations for credit unions participating in indirect vehicle leasing programs.
Collections and recovery personnel accustomed to conventional automobile loans may encounter different payoff and insurance distribution requirements when handling leased collateral.
A total-loss settlement can involve separate interests belonging to the financing institution, the titled owner, and the lessee.
For credit unions, that makes accurate identification of the vehicle’s ownership structure and the governing lease provisions particularly important before determining how insurance proceeds should be distributed.
It also underscores the importance of clearly explaining total-loss settlement procedures to members.
A consumer who sees a $57,128 insurance settlement applied against a $46,578 financial obligation may understandably question why the remaining $10,550 is being retained by another company.
The answer may be legally straightforward under the lease agreement, but that does not necessarily make it intuitive to the consumer.
–
Appeals Court Upholds Dismissal
The Third Circuit’s November 20 decision affirmed the district court’s dismissal of Ajayi’s proposed class action.
The appellate ruling was designated nonprecedential, meaning it does not establish binding precedent for future cases within the circuit.
Nevertheless, the decision provides a useful illustration of how courts may distinguish a financing institution’s secured financial interest from a leasing company’s ownership interest following a total-loss insurance settlement.
For credit union collections departments, the practical takeaway is straightforward: A paid-off lease balance and a fully compensated vehicle owner are not necessarily the same thing.
And for consumers, the case offers a reminder that paying for a vehicle’s use and insurance does not necessarily mean owning the vehicle—or the insurance proceeds remaining after its financial obligation has been satisfied.
Sources:
- U.S. Court of Appeals for the Third Circuit — Ajayi v. CULA, LLC, November 20, 2026
- U.S. District Court for the District of New Jersey — Ajayi v. CULA, LLC, February 2, 2026
Credit Union Lease Paid Off, $10,550 Left Over — Who Owns It? – Credit Union Lease Paid Off, $10,550 Left Over — Who Owns It? – Credit Union Lease Paid Off, $10,550 Left Over — Who Owns It?
Credit Union Lease Paid Off, $10,550 Left Over — Who Owns It? – Credit Union Collections – Credit Union Collectors – Lending – Auto Loan – Lawsuit – Lawsuit

More Stories
A Former NFL Star, Stolen Millions, a Rolls-Royce, and a Credit Union
CUCP Opens Registration for 2027 Collections Summit in San Antonio
Seriously Delinquent Auto Loan Debt Jumps $15 Billion as Borrower Distress Persists
Credit Washing Goes Industrial as Identical CFPB Complaints Flood the System
Credit Union Auto Loan Growth Masks Stubborn Delinquencies
Credit Union Hardship Modifications Surge 23% as Navy Federal Accounts for Much of the Increase