With traditional vehicle theft declining, NICB warns that criminals are increasingly using fraudulent loans to acquire vehicles.
–
Oak Brook, IL — October 26, 2026 — The National Insurance Crime Bureau (NICB) is warning that organized criminal networks are increasingly turning away from traditional vehicle theft and toward a potentially more profitable method of acquiring automobiles: financing them fraudulently.
According to an October 19 NICB announcement, estimated national auto lending fraud exposure has reached $10.4 billion, with losses expected to increase further during 2026.
The estimate originates from Point Predictive’s 2026 Auto Lending Fraud Trends Report, which measured exposure at $10.4 billion for 2025, compared with $9.2 billion in 2024. The increase represents approximately 13% year-over-year growth.
Importantly, the $10.4 billion figure represents estimated fraud exposure, not a confirmed total of realized lender losses.
“Vehicle finance fraud has evolved from isolated credit misrepresentations into an organized, digital criminal industry that touches dealerships, lenders and insurers,” said NICB Chief Operating Officer Timothy R. Slater.
“Stopping these networks requires shifting away from reactive, siloed defenses toward standardized and synchronized cross-industry reporting.”
–
Fraud Is Becoming a Major Factor in Auto Loan Defaults
The NICB report cites industry research suggesting that as many as 24% of auto loan defaults may be connected to fraud. Additionally, 77% of automobile dealerships surveyed reported increased fraudulent activity over the preceding two years.
First-party fraud, involving borrowers or organized groups misrepresenting income, employment, identity information or repayment intentions, now accounts for approximately 69% of estimated auto lending fraud exposure.
According to Point Predictive, income and employment misrepresentation alone accounts for 45% of total exposure, increasing 21% over the previous year.
The report also identifies a substantial increase in early payment defaults associated with suspected origination fraud. Point Predictive found evidence of origination fraud in more than 70% of early payment defaults within its analysis.
These findings suggest that a meaningful portion of what lenders initially classify as credit deterioration may actually originate with fraudulent loan applications. However, the figures are industry estimates and analytical findings, not evidence that every early default or delinquent borrower is committing fraud.
–
Synthetic Identities and Artificial Intelligence Expand the Threat
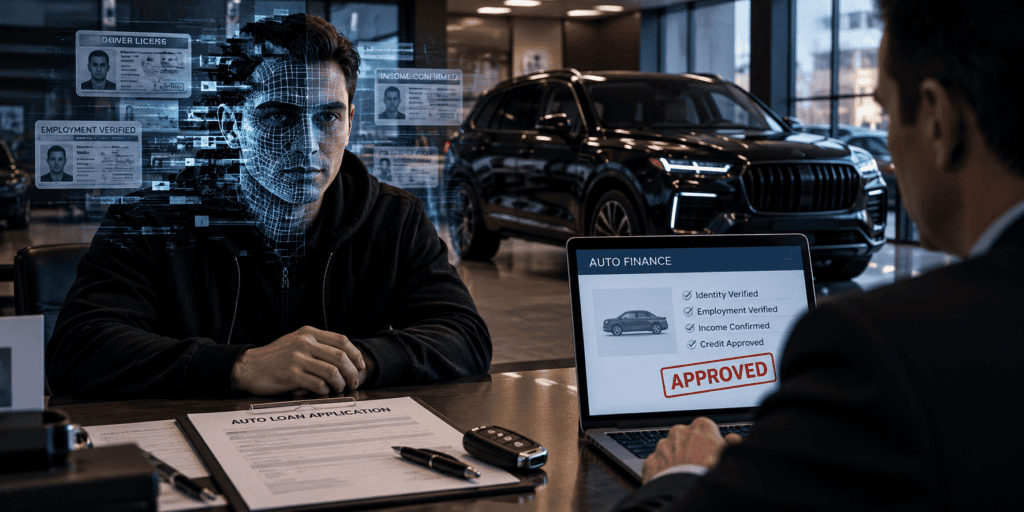
One of the fastest-evolving threats involves synthetic identity fraud, in which criminals combine legitimate personal information with fabricated identities to obtain financing.
NICB estimates that synthetic identities are involved in 80% to 85% of identity-based vehicle financing fraud schemes.
Borrowers identified as likely synthetic identities reportedly default at rates 12.5 times higher than typical consumers, with average losses ranging from $22,000 to $50,000 per case.
Artificial intelligence is also making fraudulent applications more difficult to identify.
Criminals can now generate convincing employment documentation, fabricated pay statements and other supporting materials designed to pass conventional loan verification procedures.
The report also identifies automated application attacks, fraudulent dealership websites and coordinated financing schemes involving multiple lenders.
–
Credit Washing and Bust-Out Fraud Continue to Grow
Credit washing, a practice in which borrowers or fraud rings attempt to remove legitimate negative credit information through false identity theft claims and fabricated disputes, remains another significant concern.
According to NICB, suspected credit washing increased 228% between early 2024 and mid-2025.
Fraudsters may submit forged identity theft affidavits, fabricated police reports and other false documentation to suppress derogatory credit information before applying for additional financing.
Meanwhile, organized bust-out schemes involve obtaining multiple loans or vehicles in a relatively short period, frequently across different lenders, before payments cease.
Point Predictive’s April report found that bust-out fraud had grown substantially over the previous five years, with organized rings exploiting lenders’ limited visibility into simultaneous financing activity.
Vehicles obtained through these schemes may be quickly resold, retitled, transported across state lines or exported overseas before lenders recognize the fraud.
–
Vehicle Theft Is Declining, but Fraudulent Acquisitions Are Rising
The increase in vehicle financing fraud comes as conventional automobile theft statistics have improved considerably.
According to NICB figures, reported U.S. vehicle thefts declined 23% in 2025, falling to approximately 659,880 vehicles. That followed a 17% decline in 2024, with another 21% decrease reported during the first half of 2026.
However, NICB cautions that traditional motor vehicle theft statistics do not adequately capture vehicles acquired through financing fraud.
Vehicles obtained through false identities, forged financial documents or fraudulent loan applications may not qualify as stolen vehicles under existing criminal reporting definitions.
Consequently, a vehicle acquired through fraud and subsequently shipped overseas or sold through an organized criminal network may never appear in national motor vehicle theft statistics.
NICB is advocating stronger reporting practices and updated statutory frameworks to address these gaps, including measures intended to improve the investigation and prosecution of synthetic identity fraud.
–
Implications for Auto Lenders and Repossession Companies
For automobile lenders and credit unions, the growing sophistication of financing fraud presents challenges extending beyond underwriting and loan approval.
Fraudulently financed vehicles may enter collection queues and eventually be assigned for repossession, even when the borrower identity, employment information or original transaction was fabricated.
By the time an account reaches the recovery process, the vehicle may have been transferred to another party, concealed, retitled or transported outside the country.
This creates an additional challenge for repossession companies attempting to locate collateral using borrower information that may have been unreliable from the beginning.
The NICB report does not quantify how many fraudulent auto loans ultimately result in repossession assignments or how many vehicles are successfully recovered. Nevertheless, the findings highlight the potential for fraud-related losses to extend throughout the lending, collection and collateral recovery process.
–
NICB Calls for Greater Industry Coordination
NICB is calling for increased information sharing among lenders, automobile dealerships, insurers and law enforcement agencies.
The organization works with federal, state and local investigators, including U.S. Customs and Border Protection, to identify and recover vehicles obtained through theft and financing fraud.
According to NICB, coordinated investigations in its Mid-Atlantic region alone have resulted in nearly $50 million in vehicle recoveries.
The organization is also supporting legislative efforts to strengthen identity theft enforcement and improve access to information needed to investigate organized fraud networks.
For lenders, the findings reinforce the importance of identifying fraudulent applications before funding. For recovery professionals, they underscore a growing operational problem: not every vehicle assigned for repossession is necessarily still in the possession of the person who obtained the loan.
As criminal networks become more sophisticated, the challenge may increasingly involve locating vehicles that were never financed with any intention of repayment.
The full findings are available through the NICB vehicle finance fraud initiative and Point Predictive’s 2026 Auto Lending Fraud Trends Report.
–
Editorial note: The most important qualification in this story is the distinction between fraud exposure and actual losses. NICB is publicizing Point Predictive’s $10.4 billion estimate, rather than reporting $10.4 billion in verified losses.
The New Face of Auto Theft: Financing Fraud – The New Face of Auto Theft: Financing Fraud – The New Face of Auto Theft: Financing Fraud
The New Face of Auto Theft: Financing Fraud – Credit Union Collections – Credit Union Collectors – Lending – Fraud – Fraud – Auto Loan – Dealer– Dealer – Straw Buyer – Skip – Skip– Delinquency – Repossession – Repossession

More Stories
Capital One Is Lending More to Subprime Borrowers. The Real Test Comes in 2027
STUPID STUFF FRAUDSTERS BUY: Et Tu, Fraudster?
Ally Keeps Growing as Auto Loan Delinquencies and Losses Edge Higher
When a Car Is Obtained Through Fraud, Is It Counted as Stolen?
Credit Union Employee Accused of Stealing from the Dead
Credit Union Promoted Employee Despite Fraud Warnings — Then Collapsed Under $3.5 Million in Losses